
Running a SACCO's Books and Member Savings Properly
Trust is the product
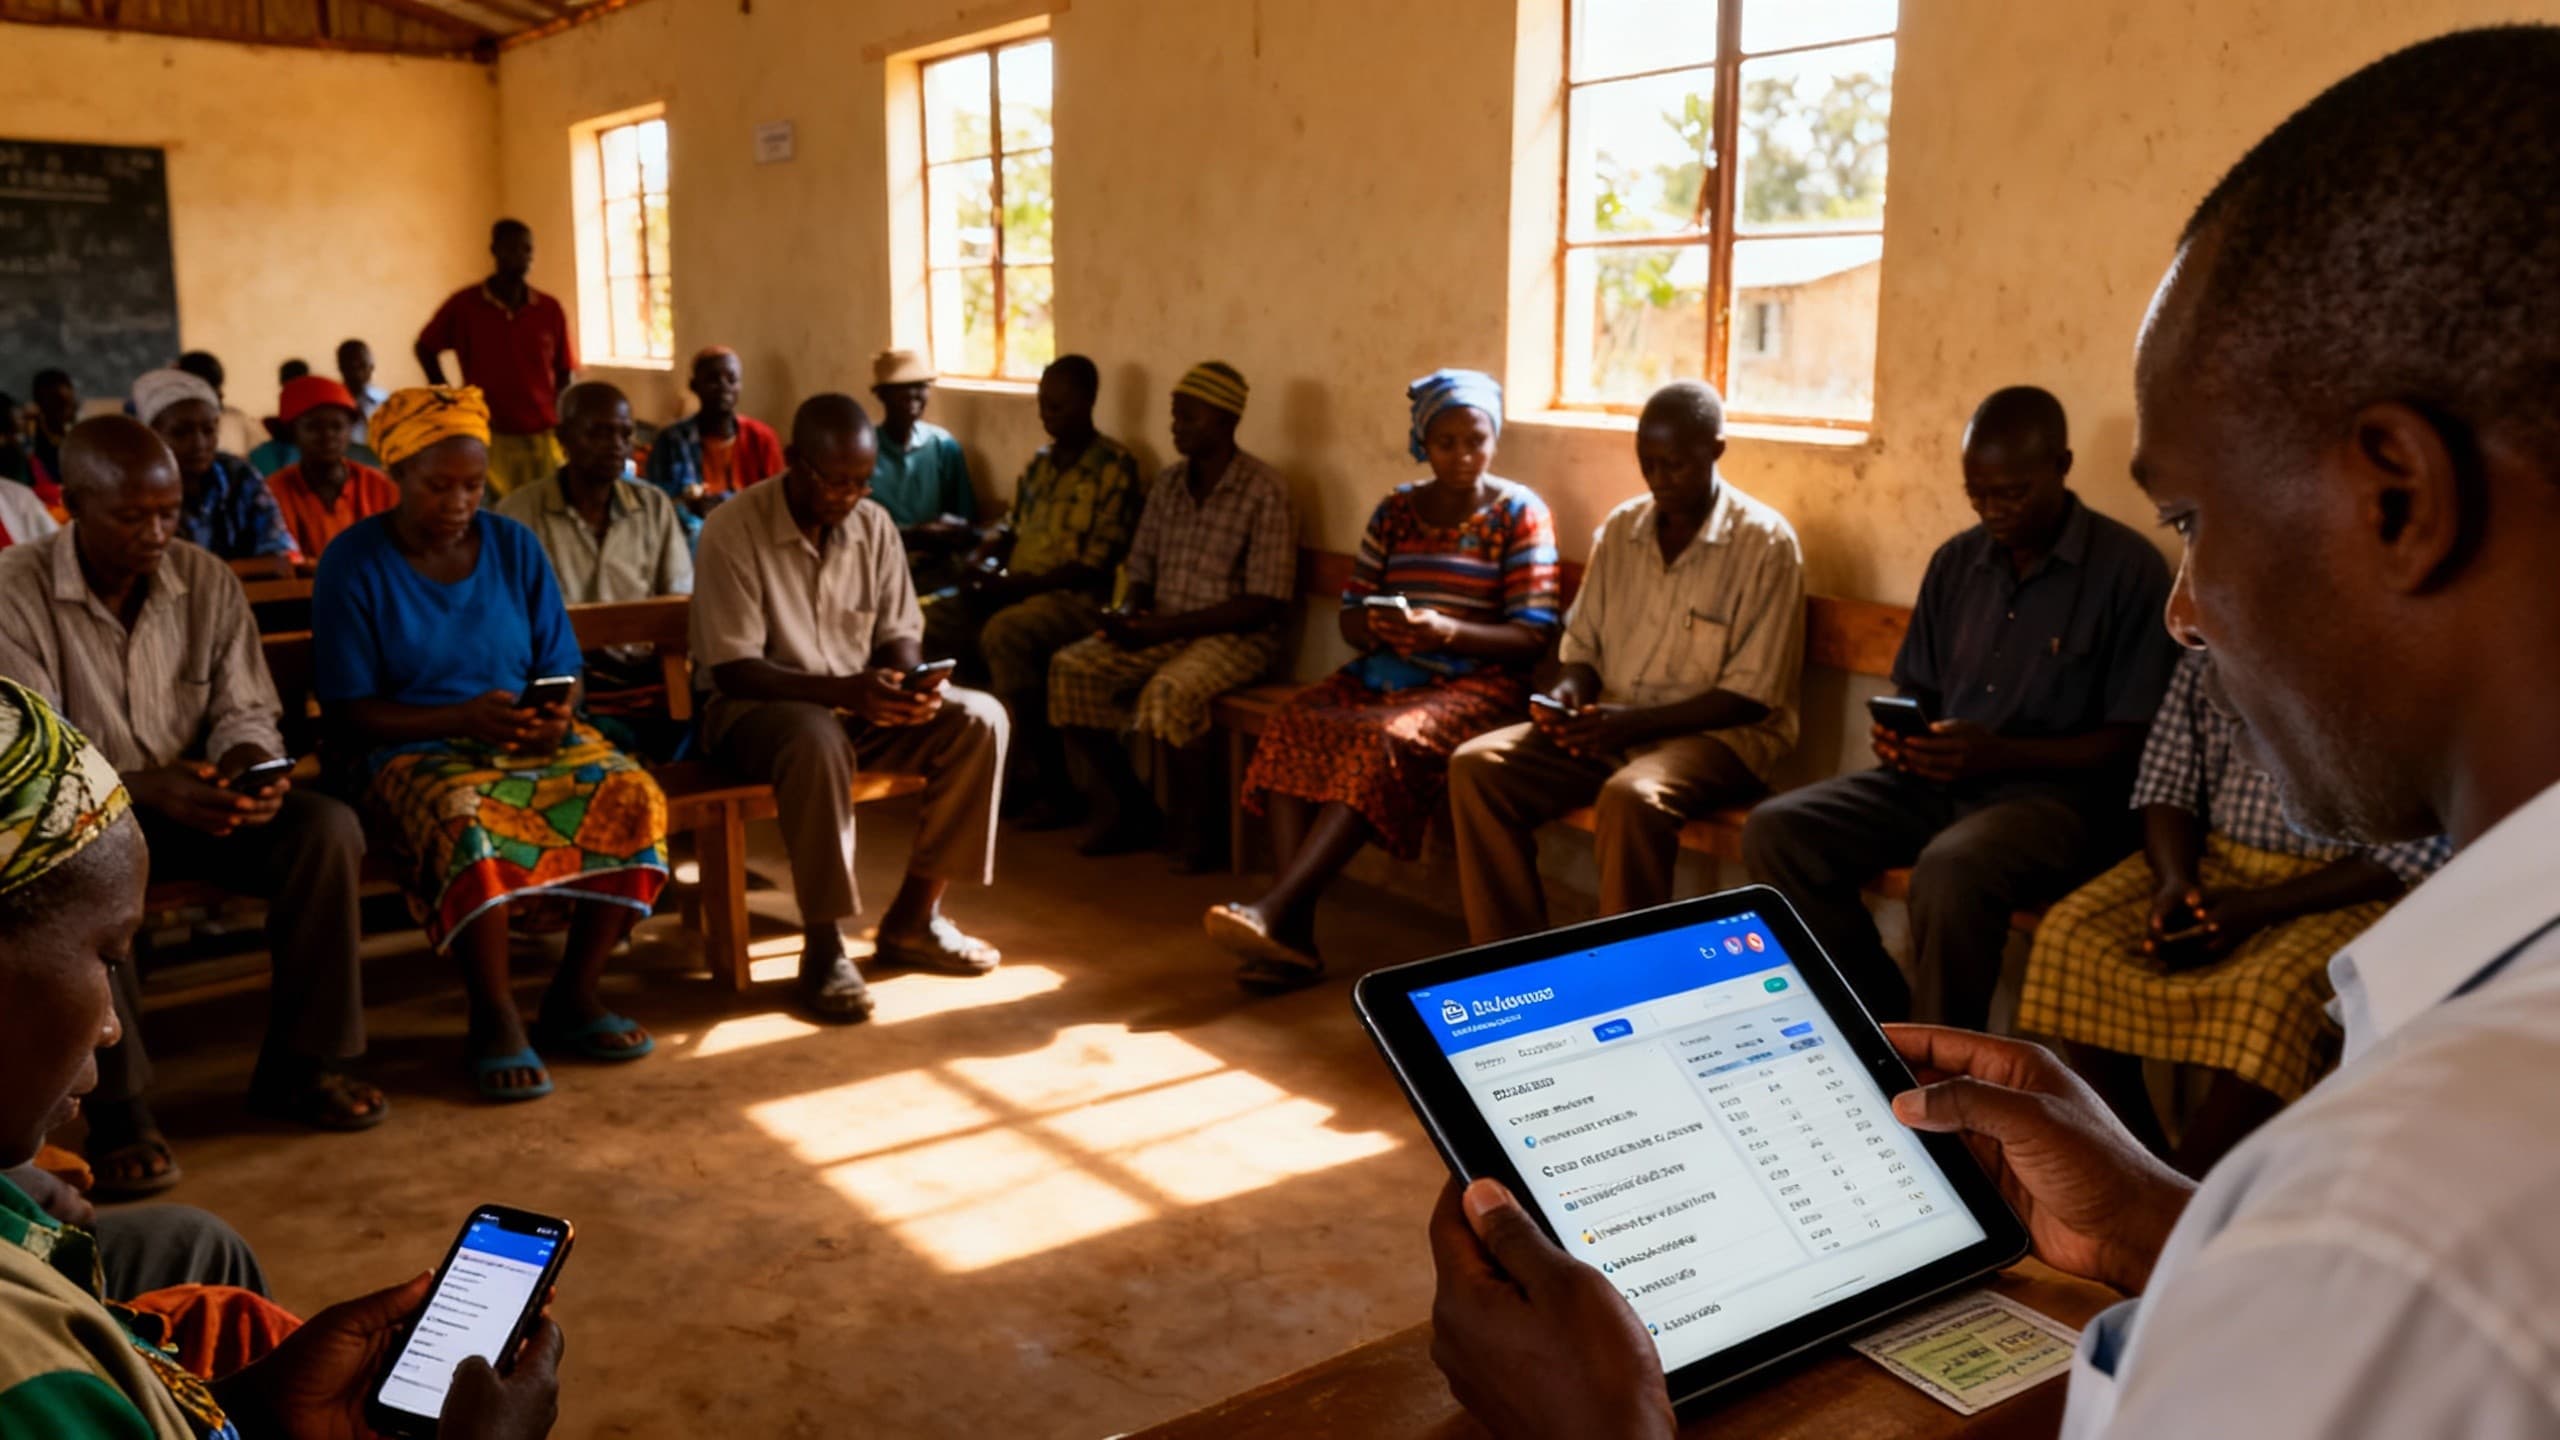
A SACCO lives on trust. Members bring their savings because they believe they will get them back, with a fair share of the profit. That trust is built or lost in the books: whether every deposit is recorded, whether loans are tracked correctly, and whether members can see their own position without having to ask.
Keep one record per member
Every member should have one record that shows their savings, shares, loans and transactions together. In BBU1 each member has exactly that. Deposits, withdrawals, share purchases and loan repayments all post to the member's record and to the SACCO's books at the same time, so the members ledger and the accounts always agree.
Loans with clear rules
Set up loan products with their interest method, term, fees and limits before any loan is given. When a loan is approved, BBU1 works out the repayment schedule from the product rules. Repayments are matched to the schedule, and loans that fall behind are visible early. Lending to members should never depend on one officer's memory or spreadsheet.
Collections and mobile money
Many members save small amounts often. Agents can record collections in the field, and where MomoPay is set up, members can pay by mobile money. Each payment lands on the right member and in the right account. The fewer times cash changes hands without a record, the safer everyone is.
Dividends without the week of sums
At the end of the year, the board decides the dividend rate. BBU1 calculates each member's dividend across all members in one run, based on their shares or savings as your rules require, ready for the board to review before anything is paid. What used to take the treasurer a week becomes an afternoon of checking.
Let members see their own position
Through the member app, members can open their savings, shares and loan balance on their phone. This reduces questions at the office and catches mistakes early, because members notice when something looks wrong. It also shows that the SACCO has nothing to hide.
Opening a member properly
Every new member should be registered with their identification, contact details, next of kin and the date they joined, with their membership fee and first shares recorded. Getting this right at the start saves arguments years later about when someone joined and what they paid.
Savings products
Many SACCOs offer more than one way to save: ordinary savings that can be withdrawn, fixed savings for a set period, and savings for a purpose such as school fees. Set each one up as its own product with its rules, so the books show clearly how much of the SACCO's money can be withdrawn at short notice and how much is committed.
Arrears and follow up
Loans in arrears are the biggest risk to a SACCO's members. Review the list of loans behind schedule every week, call members early, and record every promise to pay. Guarantors should be told when a loan they guaranteed falls behind. A SACCO that follows up within days recovers far more than one that waits for the quarterly meeting.
Reporting to members and regulators
Members deserve simple, regular reports: how much was saved, how much was lent, how much is in arrears and how the SACCO is doing. Depending on its size and type, a SACCO may also have reporting duties to regulators under Uganda's laws for cooperatives and Tier 4 institutions. Keeping the books in one system makes both kinds of reporting much easier to prepare.
Separating duties
In a small SACCO the same few people often do everything. Even so, try to separate the person who receives money from the person who records it, and both from the person who approves loans. Where that is not possible, make sure every transaction is visible to the committee, and that the audit trail shows who did what.
Moving from paper to a system
When a SACCO moves from paper books, pick a clean starting date, usually a month end. Agree every member's savings, shares and loan balances as at that date, ideally by showing members their figures and getting them confirmed. Enter loans with their remaining schedules, not their original amounts. Run the old books and the new system side by side for one month. Only switch the paper off when both agree.
Interest on savings
If the SACCO pays interest on certain savings products, the rule must be written down and applied the same way to every member. Decide how often interest is calculated, on what balance, and when it is credited. Applying it in the system rather than by hand means every member is treated equally, and every credit can be traced.
Governance habits
Separate who records money from who approves it. Reconcile cash and bank every week. Review loans in arrears at every committee meeting. Keep minutes of loan approvals. Present simple monthly reports to the board. These habits matter more than any software, and good software makes them easier to keep. More at bbu1.com/industries/sacco-cooperative.
Want to see this in your own business?
Start a free trial, or talk to us about your specific setup.
Get in touch